Introduction
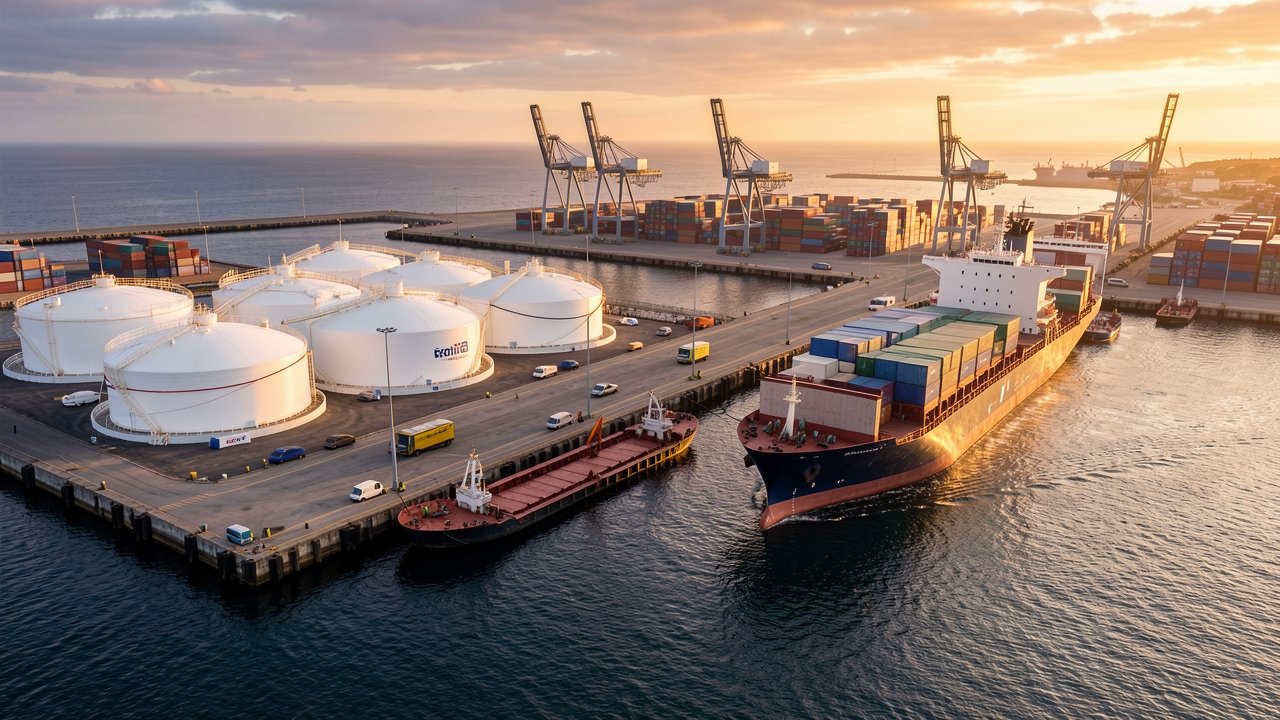
Lloyd’s Register’s latest “Fuel for Thought: Ports” report highlights a critical mismatch in the maritime sector: shipowners are rapidly ordering vessels powered by alternative fuels, while many ports lag in providing the necessary infrastructure, safety frameworks, and regulatory licences. This divergence is shaping what LR describes as one of the defining strategic challenges of the decade.
Speed of Vessel Orders vs. Shore‑Side Readiness
As of January 2026, shipyards worldwide had received orders for 1,942 alternative‑fuel‑capable vessels. The breakdown includes 1,259 LNG‑ready ships, 385 methanol‑compatible vessels, and a growing number of ammonia and hydrogen‑capable projects. In stark contrast, only 25 ports currently offer methanol bunkering, and the infrastructure for ammonia and hydrogen remains in its infancy.
Key Insight
"The vessel side of the transition is further advanced than the shore side," the report notes, underscoring the risk that ports waiting for market certainty may fall behind more proactive competitors.
Fuel Maturity Landscape
LR categorises alternative fuels by their current market penetration:
- LNG – The most mature option, supported by a near‑global bunkering network.
- Methanol – Commercially used, with limited hubs; Singapore began licensing suppliers in Jan 2026, and Shanghai recorded an 8,016‑tonne biomethanol transfer in Aug 2026.
- Ammonia – Recently achieved a first commercial bunkering operation, yet overall adoption is embryonic.
- Hydrogen – Confined mainly to demonstration projects and short‑sea routes.
- Nuclear propulsion – Presents unique challenges related to port access, licensing, and liability rather than fuel supply.
Strategic Recommendations for Ports
Kamran Ul Haq, senior vice‑president of LR Ports Advisory, stresses a balanced approach:
- Develop comprehensive risk‑assessment and regulatory frameworks before the first alternative‑fuel vessel arrives.
- Invest in workforce training and emergency‑response capabilities tailored to each fuel type.
- Foster collaboration among port authorities, shipowners, fuel suppliers, classification societies, and local emergency services.
- Prioritise a phased infrastructure plan—ports need not prepare for every fuel simultaneously, but a clear, adaptable roadmap is essential.
Opportunities Amidst the Gap
Ports that act decisively can capture early‑mover advantages, such as attracting premium freight rates, securing long‑term bunkering contracts, and positioning themselves as regional hubs for emerging fuels. Conversely, premature over‑investment carries the risk of underutilised assets if market uptake slows.
Conclusion
The coming decade will test the resilience and foresight of ports worldwide. Aligning infrastructure development with the accelerating pace of alternative‑fuel vessel orders is not merely a regulatory imperative—it is a competitive necessity for ports aiming to remain relevant in a decarbonising maritime industry.