Overview
Turkey has emerged as a decisive player in the 2026 global crude market, posting a 31.4% year‑on‑year increase in exports during the January‑September period. The rebound follows a modest decline in 2024 and a modest rise in 2025, signalling a robust recovery for the Mediterranean oil hub.
Export Performance by Region
According to shipbroker Banchero Costa, Turkish crude exports reached 24.1 million tonnes (mt) in the first three quarters of 2026, up from 18.3 mt a year earlier. The surge is primarily linked to two feedstocks:
- Azeri BTC grade: 18.7 mt, transported via the 1,768 km Baku‑Tbilisi‑Ceyhan (BTC) pipeline.
- Kirkuk grade: The balance of the cargoes, sourced from the 970 km Kirkuk‑Ceyhan pipeline.
Turkey’s role as a conduit for Azerbaijan and northern‑Iraq crude underscores its strategic position despite negligible domestic reserves.
Global Crude Loading Trends
While Turkish exports surged, total global seaborne crude loadings fell 6.1% YoY to 1,547.6 mt (excluding cabotage). Key regional shifts include:
- Arabian Gulf exports down 29.1% to 464.5 mt, reflecting disruptions from the Persian Gulf conflict.
- Russian‑origin cargoes up 8.3% to 187.1 mt, aided by the CPC terminal route.
- South American shipments rose 33.1% to 212.3 mt.
- U.S. exports increased 10.5% to 150.5 mt.
- West African volumes slipped 10.2% to 118.7 mt.
- ASEAN exports grew 8.3% to 86.2 mt (including trans‑shipped cargoes).
Import Demand Landscape
Global seaborne crude imports contracted 5.4% YoY to 1,549.2 mt in the same period. The leading single‑country importer remained Mainland China, accounting for 18.8% of the market, but its volumes fell 20.7% YoY to 291.8 mt. The EU27 bloc collectively imported 350.9 mt, a modest 1.3% increase, representing the largest regional share at 22.6%.
- ASEAN imports down 8.0% to 198.7 mt.
- South Korea imports down 10.7% to 92.0 mt.
- U.S. imports rose 4.0% to 96.8 mt.
- Japan imports fell 13.5% to 71.1 mt.
Implications for the Mediterranean Tanker Market
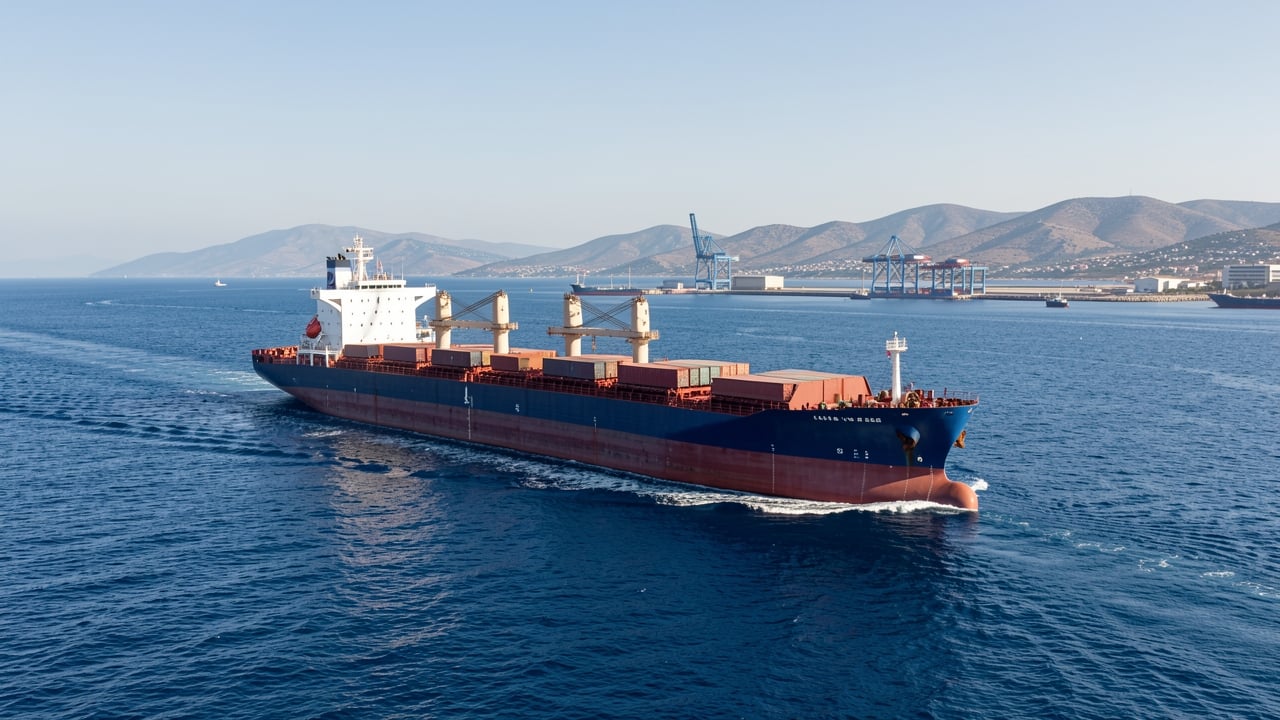
The Turkish rebound is reshaping tanker routes across the Mediterranean. Increased loading at Ceyhan and other Turkish terminals is expected to boost demand for VLCC and Suezmax vessels, while also prompting a re‑allocation of fleet capacity previously tied to Arabian Gulf shipments.
Stakeholders should monitor the evolving supply‑demand balance, especially as geopolitical tensions continue to affect Gulf output and as Turkish infrastructure further integrates regional crude streams.
Outlook
Analysts anticipate that if regional stability improves, Turkish exports could maintain double‑digit growth through the remainder of 2026. The sustained flow of Azeri BTC and Iraqi Kirkuk grades will likely keep the Mediterranean a focal point for global crude logistics.